
State of the Electronic Components Market: September 2026
Price Inflation Surges as Lead-Time Pressure Eases
Lytica is the world’s only buyer-powered agentic AI supply chain platform, built on real customer transactional data. The SupplyLens™ Pro platform gives procurement teams the clarity and leverage to cut costs in negotiations, reduce supply risk, and make good decisions from design to source. The world’s top OEMs and EMS providers tell us the same thing: before Lytica, they were operating in the dark.
As a result of this unique position in the marketplace, we’ve been able to work with hundreds of customers in analyzing over $550+ billion in electronics spend. We’ve curated up-to-date insights on the state of the electronic component market and will be sharing them with you each month here. Subscribe today to receive these each month upon release.
Lytica’s component basket of goods used in our analysis is comprised of 165,000 electronic components across more than 30 categories, consisting of the most popular devices used by our customers. These indices are intended to show trends in the market. Individual component and BoM analysis is offered by Lytica as a service to our customers. Request a demo to see it in action.
⚡ Key Takeaway Summary
September produced the strongest overall price increase in the 2026 dataset. Lytica’s overall electronic component price index jumped to +2.98% month over month, up from +1.23% in August. Price increases were nearly universal: 30 of the 31 categories tracked in this report moved higher, and only RF/MW declined.
Lead times moved sharply in the opposite direction. The overall lead time index fell to +1.89% from +12.40% in August. Twenty-three categories posted longer lead times, six compressed, and two were flat. Magnetic (+16.2%), Optomechanical (+14.7%), and Processor (+10.3%) were the only categories with double-digit extensions.
Stock availability remained broadly healthy at 95.23% overall, slightly above August’s 95.0%. Nineteen categories show availability of at least 95%, but concentrated pockets of tightness remain in Battery (82.0%), Resistor (84.3%), Thermal Management (88.9%), Frequency Control (89.0%), and Connector (89.6%).
Optomechanical is September’s clearest combined risk signal: price increased +6.2% and lead time extended +14.7%, even with 96.7% current availability. Diode (+6.6%), Transistor (+5.5%), and Power Discrete (+5.3%) also show that repricing has broadened across discrete and power semiconductor categories.
Action required: Prioritize Optomechanical, Diode/Power Discrete/Transistor, Resistor, Magnetic, and Processor for Q4 supply and cost reviews. Maintain forward Memory coverage and keep Battery on the availability watch list. September’s price breadth warrants MPN-level validation even where lead times are improving.
What Drove Electronic Component Price Changes in September 2026?
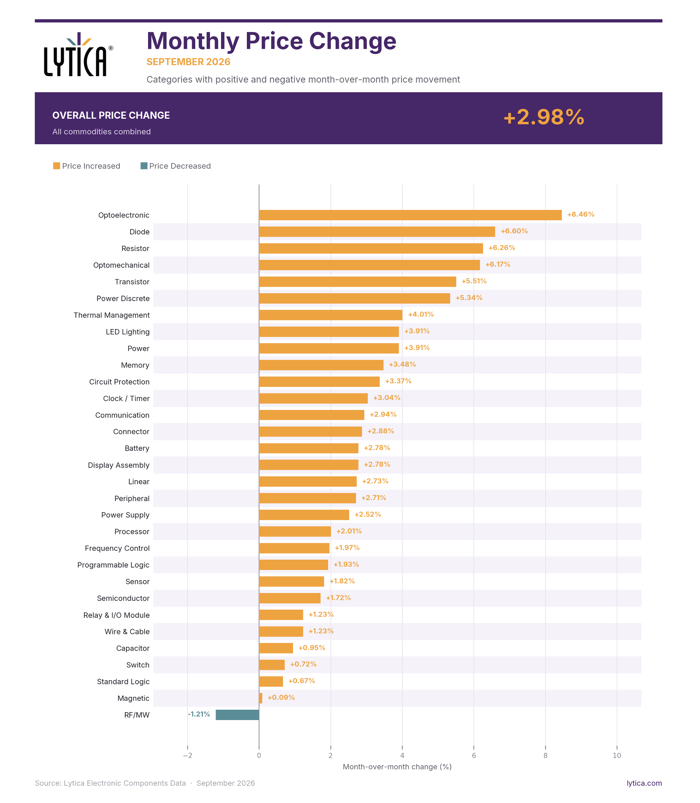
September was a clear repricing month. The overall price index rose to +2.98% from +1.23% in August – the highest monthly reading in the 2026 dataset. Thirty of the 31 tracked categories increased, and 20 categories rose by at least +2.0%. The breadth and size of the moves are materially different from August.
Overall price index: +2.98% MoM, up from +1.23% in August
Highest increase: Optoelectronic +8.5%
Diode +6.6%; Resistor +6.3%; Optomechanical +6.2%
Transistor +5.5%; Power Discrete +5.3%
Thermal Management +4.0%; LED Lighting and Power +3.9%
Twenty categories increased by at least +2.0%; 12 increased by at least +3.0%
Only decline: RF/MW -1.2%
Optoelectronic: September’s Largest Price Increase
Optoelectronic prices increased +8.5% in September, up sharply from +1.2% in August. Lead time increased a much more modest +3.6%, while availability remained high at 97.4%. The combination points to repricing and strong demand more than broad stock depletion.
External market signals support that direction. Reuters reported in September that STMicroelectronics expects optical-link chips to account for roughly 80% of its projected AI data-center revenue in 2027. TrendForce also identified optical interconnect as a major contributor to strengthening AI-infrastructure demand.
Procurement implication: Treat Optoelectronic as an active cost-review category. High current availability does not eliminate the need to validate pricing at the MPN level, especially for AI, networking, and high-speed connectivity applications.
Discrete and Power Semiconductors: Repricing Broadens
September showed a broad step-up across discrete and power categories: Diode increased +6.6%, Transistor +5.5%, Power Discrete +5.3%, and Power +3.9%. Lead-time growth was much smaller than the price movement for most of these categories, indicating that cost pressure is not being driven solely by worsening delivery windows.
TrendForce reported in September that record foundry revenue was being supported by AI and HPC demand, including rising requirements for PMICs and power discretes. Its AI infrastructure research also noted tighter power-semiconductor supply, longer order visibility, and supplier price increases as data-center power architectures scale.
Procurement implication: Review discrete and power semiconductor pricing together rather than part-by-part. Validate supplier notices, contract clauses, and alternate-source coverage before assuming the September increases are temporary.
Memory: Inflation Persists as Delivery Pressure Eases
Memory prices increased +3.5% in September, down modestly from +4.0% in August. The more notable change was lead time, which fell from +18.2% in August to only +0.4% in September, while availability remained healthy at 95.6%.
TrendForce’s September outlook continued to show an undersupplied memory market driven by AI and server demand, with conventional DRAM contract prices forecast to rise 10-15% quarter over quarter in 4Q26 and NAND Flash 15-20%. Micron also reported expanding customer commitments tied to AI memory demand at the end of September.
Procurement implication: Lead-time normalization should not be read as a reversal in the Memory cycle. Forward coverage remains important where server, networking, or AI workloads compete for capacity.
Which Electronic Component Categories Experienced the Largest Lead Time Extensions in September 2026?
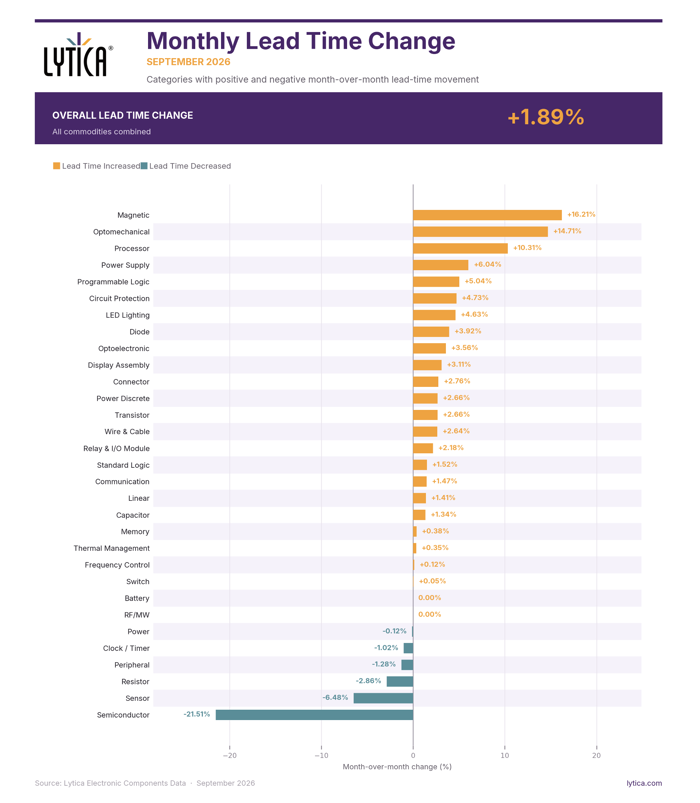
September’s lead-time picture is the opposite of August. The overall index fell to +1.89% from +12.40%, and the broad market-wide extension seen in August narrowed to a smaller set of categories. Twenty-three categories still moved higher, but six compressed and two were flat.
Overall lead time index: +1.89% MoM, down from +12.40% in August
Magnetic: +16.2%
Optomechanical: +14.7%
Processor: +10.3%
Power Supply: +6.0%
Programmable Logic: +5.0%
Circuit Protection: +4.7%; LED Lighting +4.6%
Largest compressions: Semiconductor -21.5%; Sensor -6.5%; Resistor -2.9%
Battery and RF/MW were flat
⚠️ Risk Alert: Lead-Time Pressure Narrows to a Handful of Categories
August’s broad lead-time wave largely unwound in September. Several categories that had posted double-digit extensions in August normalized sharply, including Semiconductor, Sensor, Memory, and Power. The remaining pressure is now much more concentrated.
Magnetic and Optomechanical moved in the opposite direction. Magnetic lead time increased +16.2% with almost no current price movement, while Optomechanical posted both a +14.7% lead-time increase and a +6.2% price increase. Processor also remained elevated at +10.3%.
What to watch: September is not a market-wide lead-time warning. Procurement teams should separate broad cost inflation from category-specific replenishment risk and focus forward-coverage work on the few categories where delivery windows are still stretching materially.
Magnetic and Optomechanical: September’s New Lead-Time Hotspots
Magnetic lead times increased +16.2%, the largest extension in September. Price moved only +0.1% and availability was 94.6%, creating a classic early-warning pattern where delivery pressure has not yet translated into material pricing.
Optomechanical is more advanced in the cycle: lead time increased +14.7%, price increased +6.2%, and availability was 96.7%. This is an active cost-and-delivery exposure rather than a watch-only signal.
Semiconductor and Resistor: Lead Times Ease, Pricing Does Not
Semiconductor lead time compressed -21.5% after increasing +19.4% in August, while availability improved from 91.4% to 94.7%. Yet price still increased +1.7%. Resistor shows an even stronger disconnect: lead time compressed -2.9%, but price increased +6.3% and availability remained only 84.3%. September reinforces that price pressure can persist after delivery windows begin to normalize.
What Is the Current Stock Availability for Electronic Components in September 2026?
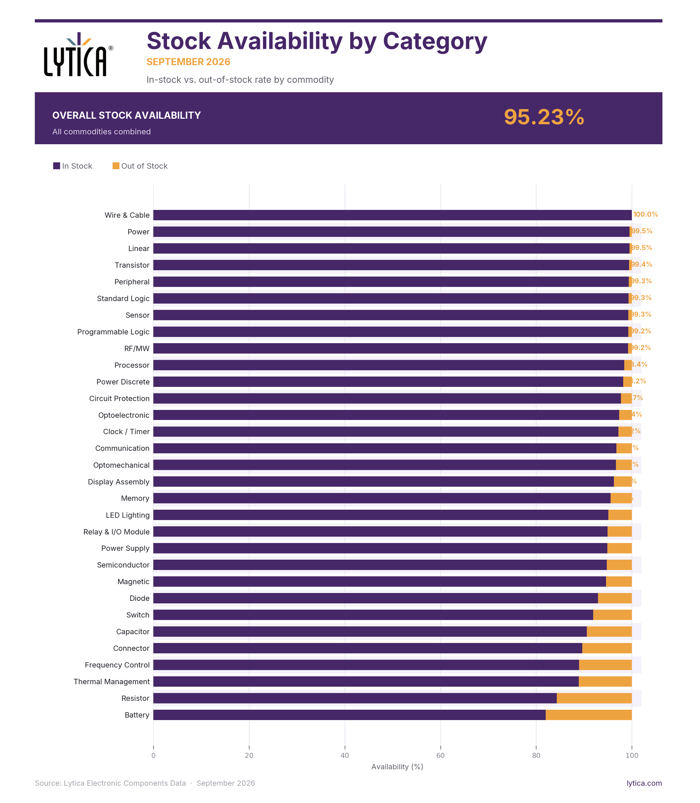
Overall stock availability edged higher to 95.23% in September from 95.0% in August. Nineteen of the 31 tracked categories show availability of at least 95%. The headline remains healthy, but the categories below 90% deserve focused attention because several are also showing meaningful price pressure.
Battery: 84.2% -> 82.0%
Resistor: 84.7% -> 84.3%
Thermal Management: 91.1% -> 88.9%
Connector: 90.6% -> 89.6%
Semiconductor: 91.4% -> 94.7%
Wire & Cable: held at 100.0%
Tightest Availability Categories
Battery – 82.0%: The lowest availability in September. Price increased +2.8% while lead time was flat, so the primary signal remains constrained current stock rather than worsening replenishment.
Resistor – 84.3%: Still the second-tightest category and now paired with a +6.3% price increase, even as lead times compressed.
Thermal Management – 88.9%: Availability deteriorated from 91.1% in August while price increased +4.0%. Lead time was nearly flat.
Frequency Control – 89.0%: Availability remains below the market average, but the extreme August lead-time signal has normalized to +0.1%.
Connector – 89.6%: Availability slipped below 90% while price increased +2.9% and lead time +2.8%.
Key point: September’s 95.23% overall availability masks concentrated tightness. The broad market is well supplied today, but Battery, Resistor, Thermal Management, Frequency Control, and Connector remain materially below the market average.
How Has the Overall Electronic Component Price Index Trended in 2026?
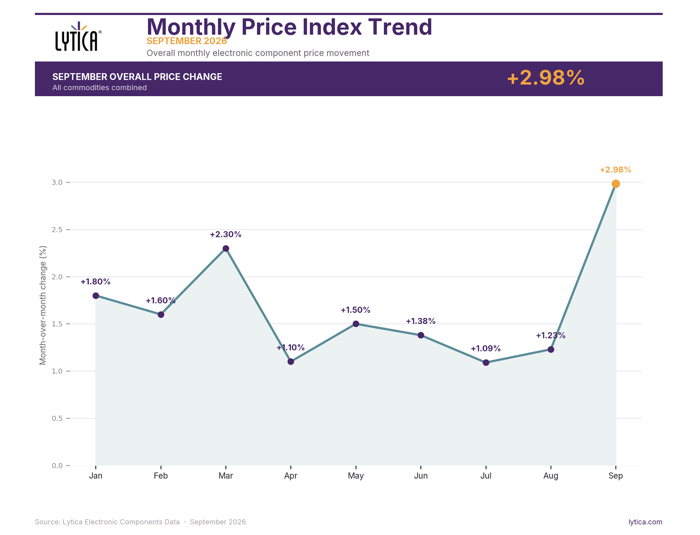
September’s +2.98% reading is the highest overall monthly price increase in the 2026 dataset and more than double August’s +1.23%. The sequencing is notable: August showed the broadest lead-time expansion of the year, while September shows the strongest broad-based repricing even as the overall lead-time index normalizes.
Market read: September is primarily a repricing month, not a market-wide shortage month. Category-level behavior remains uneven, so procurement teams should not assume a simple one-month relationship between lead times and prices.
What Should Procurement Leaders Do Right Now? September 2026 Action Items
🔴 Urgent – Act This Month
Optomechanical: Price +6.2%, lead time +14.7%, availability 96.7%. Revalidate pricing and delivery commitments now; this is September’s clearest combined cost-and-replenishment signal.
Diode / Power Discrete / Transistor: Prices increased +6.6%, +5.3%, and +5.5%, respectively. Review supplier price changes, contracted terms, and alternate-source coverage across the discrete semiconductor portfolio.
Resistor: Price +6.3% with only 84.3% availability, despite lead-time compression. Treat current pricing as an active cost exposure rather than assuming delivery improvement will immediately reverse it.
Magnetic / Processor: Lead times increased +16.2% and +10.3%. Secure critical demand before these delivery-window signals begin to affect pricing or availability.
🟡 Monitor Closely – 30-60 Day Window
Thermal Management: Price +4.0% and availability 88.9%. AI infrastructure continues to support demand for cooling and power-density solutions, even though September lead time was nearly flat.
Memory: Price +3.5% with 95.6% availability and normalized lead time. Maintain forward coverage where AI/server demand competes for capacity.
Battery: Availability fell to 82.0%, the lowest in the basket, while price increased +2.8%. Lead time was flat, so monitor inventory availability and supplier-specific exposure.
Stable / Improving – Keep on the Watch List
Semiconductor / Sensor: Lead times compressed -21.5% and -6.5%, respectively. Semiconductor availability also improved to 94.7%.
RF/MW: The only price decline in September at -1.2%, with flat lead time and 99.2% availability.
Power: Price increased +3.9%, but lead time was essentially flat (-0.1%) and availability remained 99.5%. Treat it as a cost issue more than a current delivery-risk issue.
FAQ: Electronic Component Market - September 2026
Q: How did electronic component prices change in September 2026? Lytica’s overall electronic component price index increased +2.98% month over month in September, up from +1.23% in August and the highest monthly reading in the 2026 dataset. Optoelectronic recorded the largest increase at +8.5%, followed by Diode (+6.6%), Resistor (+6.3%), Optomechanical (+6.2%), Transistor (+5.5%), and Power Discrete (+5.3%). Thirty of 31 categories increased. Q: Which electronic components experienced the largest lead-time extensions in September 2026?
Magnetic recorded the largest increase at +16.2%, followed by Optomechanical (+14.7%) and Processor (+10.3%). The overall lead-time index was +1.89%, down sharply from +12.40% in August. Semiconductor (-21.5%) and Sensor (-6.5%) posted the largest compressions.
Q: Is electronic component availability getting better? At the overall level, availability remained strong and edged up from 95.0% in August to 95.23% in September. However, Battery (82.0%), Resistor (84.3%), Thermal Management (88.9%), Frequency Control (89.0%), and Connector (89.6%) remain materially tighter than the overall market. Q: Why are prices rising while overall lead times are easing? September shows that price and lead time do not move together uniformly. Some categories are repricing even as delivery windows normalize, reflecting supplier pricing actions, prior tightness, capacity allocation, and demand mix. Resistor is the clearest example: price increased +6.3% while lead time compressed -2.9%. Q: What changed most from August to September? The market flipped from a broad lead-time event to a broad pricing event. Overall lead time fell from +12.40% to +1.89%, while the price index jumped from +1.23% to +2.98%. Availability stayed broadly healthy. The result is a market where cost pressure is widespread, but replenishment risk is concentrated in a smaller set of categories.
Sources and References
The following sources were consulted to provide broader market context alongside Lytica’s proprietary September 2026 data. August-to-September comparisons use Lytica’s August report as the prior-month published reference.
Lytica, State of the Electronic Components Market: August 2026
TrendForce, AI Server Demand Sustains Memory Contract Price Increases in 4Q26, September 30, 2026
Reuters, STMicro’s 2027 AI revenue to be four-fifths optics, CFO says, September 9, 2026
onsemi, onsemi Charts Path to Power the Next Decade of Innovation, September 16, 2026
TrendForce, Japanese and Korean MLCC Makers Cut Consumer Supply to Focus on AI, September 24, 2026